 ultimate-guide
Is Hyperbaric Oxygen Therapy Covered by Insurance? 2026 Guide
Table of Contents
- What Hyperbaric Oxygen Therapy Is and Why Coverage Varies
- FDA-Approved Conditions for HBOT That Insurers Recognize
- Medicare, Commercial Insurance, and Medical Necessity Criteria
- The Cost of Hyperbaric Oxygen Therapy Out of Pocket
- How to Verify Your Insurance Benefits Before Treatment
- How to Appeal an Insurance Denial for HBOT
- In-Network vs. Out-of-Network and Off-Label Coverage
- Conclusion
- Frequently Asked Questions
Last Updated: September 27, 2026
What Hyperbaric Oxygen Therapy Is and Why Coverage Varies
Whether is hyperbaric oxygen therapy covered by insurance depends almost entirely on why it's prescribed. Hyperbaric oxygen therapy (HBOT) is a medical treatment in which a patient breathes pure oxygen inside a pressurized chamber, raising oxygen levels in the bloodstream well above normal. Insurers cover it when the diagnosis appears on their approved list, and deny it when it doesn't.
How HBOT Works in Plain Terms
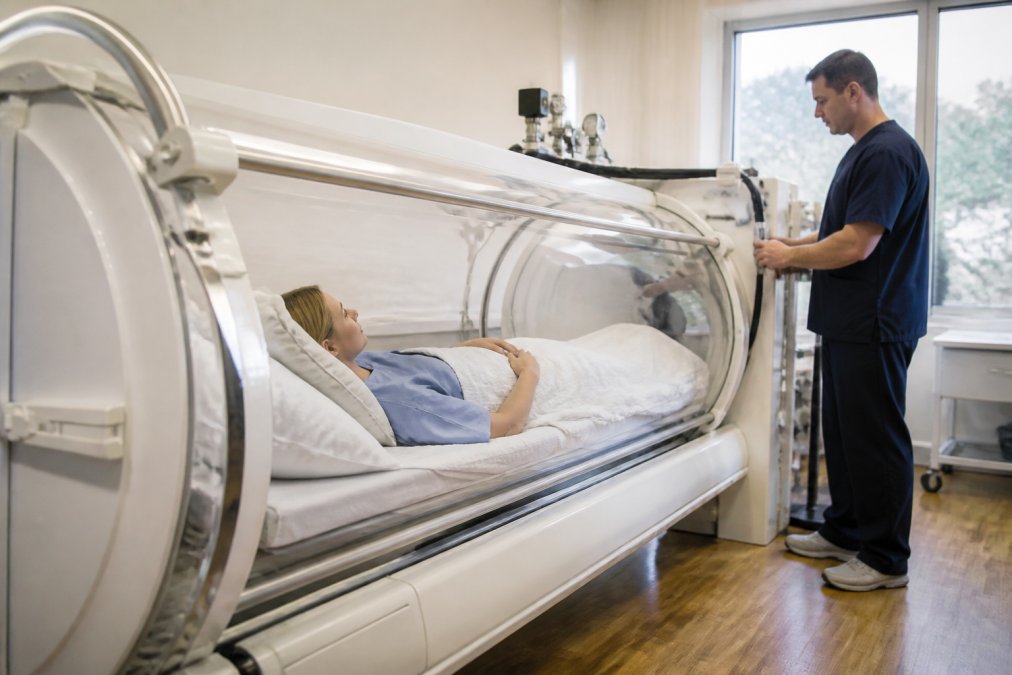
The chamber raises atmospheric pressure while you breathe pure oxygen. Under pressure, oxygen dissolves directly into plasma rather than riding only on red blood cells, which lets it reach tissue with poor circulation. A typical course runs multiple sessions, often daily, and each session lasts roughly one to two hours. The Undersea and Hyperbaric Medical Society's clinical resources maintains the reference list of indications that most payers build their policies around.
Why Insurers Treat HBOT Differently Than Other Treatments
HBOT is expensive to deliver, requires specialized equipment and trained staff, and its evidence base is uneven across conditions. Payers respond by tying coverage to a fixed list of diagnoses rather than approving case by case. A common mistake is assuming a physician's recommendation guarantees payment. It doesn't, the plan's medical policy decides, and the physician's note is only supporting evidence.
FDA-Approved Conditions for HBOT That Insurers Recognize
The FDA-approved conditions for HBOT anchor nearly every coverage decision, and insurers generally mirror that list. Commonly recognized indications include:
- Carbon monoxide poisoning
- Decompression sickness
- Non-healing diabetic wounds of the lower extremity
- Radiation injury to tissue, including delayed radiation damage
- Chronic osteomyelitis
- Crush injuries and compromised skin grafts or flaps
- Gas gangrene and certain necrotizing soft-tissue infections
Medicare, Commercial Insurance, and Medical Necessity Criteria
Medical necessity is the standard both Medicare and commercial plans apply, and it's the most contested part of any HBOT claim. The payer asks whether treatment is reasonable, necessary, and supported by clinical documentation for that patient. Meeting that bar requires more than a diagnosis: evidence standard care was tried, signs of healing are stalled, and the condition meets the plan's written criteria.
Medicare Coverage Guidelines
Medicare coverage guidelines for HBOT are set nationally through a coverage determination, then applied by the local contractor processing the claim. National coverage policy lists the indications Medicare recognizes, and the treating facility must document that the patient's condition fits one of them. Verify the current determination on the official Medicare site rather than a summary. A physician referral and clinical documentation supporting medical necessity are required before treatment begins.
Commercial Insurance and Prior Authorization
Commercial insurance almost always requires prior authorization before HBOT begins:
- The physician submits a referral with the diagnosis and clinical history
- The plan reviews against its medical policy for that indication
- The plan approves a set number of treatment sessions
- Additional sessions require a new request with evidence of progress
The Cost of Hyperbaric Oxygen Therapy Out of Pocket
The cost of hyperbaric oxygen therapy out of pocket varies widely by facility, region, and whether treatment is hospital-based or clinic-delivered. Rather than quote a figure that won't match your situation, understand the structure of what you'll owe.
When HBOT is covered, your share typically includes:
- Deductible: the amount you pay before the plan begins covering
- Co-insurance: the percentage of the allowed amount you owe after the deductible
- Co-pay: a fixed amount per session, if your plan uses one
- Out-of-network balance billing: the gap between what the provider charges and what the plan allows, when you go outside the network
How to Verify Your Insurance Benefits Before Treatment
Verification starts before the first session, not after the first bill. Call your plan and the treating facility, and get answers in writing:
- Is HBOT a covered service under my specific benefit plan?
- Which diagnoses does my plan's medical policy approve for HBOT?
- Is prior authorization required, and who submits it?
- Is the treating facility in-network?
- What will my deductible, co-insurance, and co-pay be per session?
- How many sessions are approved, and how do I request more?
How to Appeal an Insurance Denial for HBOT
An appeal is a formal request to reverse a denial, and it succeeds most often when it directly answers the reason the claim was rejected.
Internal Appeal vs. External Review
There are two distinct stages, and confusing them costs time.
The Peer-to-Peer Review Option
Before or alongside a written appeal, ask whether a peer-to-peer review is available. This is a phone call between your treating physician and the plan's medical reviewer, often the fastest path to a reversal when the denial rests on clinical judgment rather than a missing document. Not every plan offers it, and it usually must be requested by the physician's office, so ask the facility's billing team.
What a Strong Appeal Letter Contains
A letter of medical necessity that wins does three things:
- Names the policy, cites the plan's own medical policy by title and the specific criteria the patient meets
- Maps the chart to the criteria, quotes the clinical notes that satisfy each requirement (failed standard therapy, stalled wound measurements, imaging findings)
- Cites supporting evidence, references the payer's own policy language or widely recognized clinical references rather than general claims that "the treatment works"
Documentation Checklist for Your Appeal
- Copy of the denial letter with the stated reason and deadline
- The plan's written medical policy for HBOT and the relevant diagnosis
- Letter of medical necessity from the treating physician, citing the policy criteria
- Clinical notes showing the diagnosis and symptom history
- Evidence that standard treatments were tried and failed
- Wound measurements or imaging showing measurable signs of healing are stalled
- Prior authorization request and the plan's response, if applicable
- Records of all calls with reference numbers and representative names
- Peer-to-peer review request, if the plan offers one
In-Network vs. Out-of-Network and Off-Label Coverage
In-network versus out-of-network changes what you pay even when the treatment itself is covered. An in-network facility has a contract with your plan that sets the allowed amount, and you owe only your deductible, co-insurance, or co-pay. An out-of-network facility has no such contract, so the plan may reimburse a smaller share and the provider can bill you for the difference.
Hospital-Based vs. Freestanding Facilities
This nuance can swing your bill by thousands of dollars across a multi-session course.
Off-Label and Experimental Coverage
Coverage for off-label conditions is the other gap. Off-label means the treatment is used for a diagnosis not on the FDA-cleared or plan-approved list. Some plans will consider off-label HBOT when a physician submits peer-reviewed evidence, but many will not, and plans frequently classify off-label HBOT as "experimental" or "investigational," a separate denial category from "not medically necessary."
| Scenario | Coverage Likelihood | What You Owe | Key Action |
|---|---|---|---|
| FDA-approved diagnosis, in-network, prior auth obtained | Covered | Deductible, co-insurance, co-pay | Confirm authorization before session one |
| FDA-approved diagnosis, out-of-network | Partial to none | Balance billing plus higher share | Verify out-of-network benefit first |
| FDA-approved diagnosis, hospital-based vs. freestanding | Varies by contract | Facility fee may apply at hospital-based sites | Confirm the specific location is contracted |
| Off-label diagnosis, plan allows with evidence | Case by case | Depends on approval outcome | Submit peer-reviewed evidence with appeal |
| Off-label diagnosis, plan classifies as experimental | Usually denied | Full bill if appeal fails | Challenge the evidence standard, not just the chart |
| No prior authorization obtained | Often denied | Full bill if appeal fails | Appeal with medical necessity letter |
Conclusion
The gap between a covered HBOT claim and a denied one usually comes down to preparation: matching the diagnosis to the plan's approved list, securing prior authorization, and documenting medical necessity before treatment starts. Facilities that want to offer hyperbaric and recovery services need equipment and a business model that support that care properly. Eternall Wellness provides commercial-grade hyperbaric chambers and multi-modality recovery systems, with financing options that preserve capital and a focus on evaluating each system as a revenue-generating service rather than a one-time purchase.
Frequently Asked Questions
How much does one session of hyperbaric oxygen therapy cost?
Out-of-pocket costs for hyperbaric oxygen therapy vary widely by facility, location, and whether the chamber is hospital-based or part of a standalone clinic. Hospital-based treatments are typically billed at higher rates than freestanding centers. Because pricing depends on the provider and the number of treatment sessions prescribed, ask each facility directly for a self-pay rate and a written estimate. If you have insurance, request a cost estimate that reflects your deductible, co-insurance, and any prior authorization requirements before you begin.
What documentation is required for insurance approval of HBOT?
Insurers generally want clinical documentation that establishes medical necessity: the diagnosis, relevant imaging or lab results, prior treatments tried and failed, and a physician referral or prescription specifying the number of treatment sessions. For wound-related conditions, many plans also require measurable signs of healing progress documented at set intervals. A specific CPT code and diagnosis code must match the plan's medical policy. Incomplete documentation is one of the most common reasons for a claim denial, so review your plan's medical policy before submitting.
Is hyperbaric oxygen therapy considered experimental for some conditions?
Yes. Many insurers classify HBOT as experimental or investigational for conditions outside their list of FDA-approved indications, which means they will not cover it for those uses. This gap is common for off-label applications such as certain neurological or inflammatory conditions. Coverage for off-label use depends on your specific benefit plan and its medical policy. If your condition is not on the approved list, request the plan's written medical policy and ask your physician whether an appeal with supporting clinical documentation is worth pursuing.
How do you qualify for hyperbaric oxygen therapy under Medicare?
Medicare Part B may cover HBOT when it is medically necessary for a qualifying condition and the treatment is furnished under a physician's supervision. Medicare rules require the specific condition to fall within its covered indications and the documentation to support medical necessity. Because Medicare coverage guidelines and local coverage determinations can differ by region and change over time, confirm your situation directly with Medicare or your Medicare Advantage plan before starting treatment. A physician referral and clear clinical documentation are typically required.